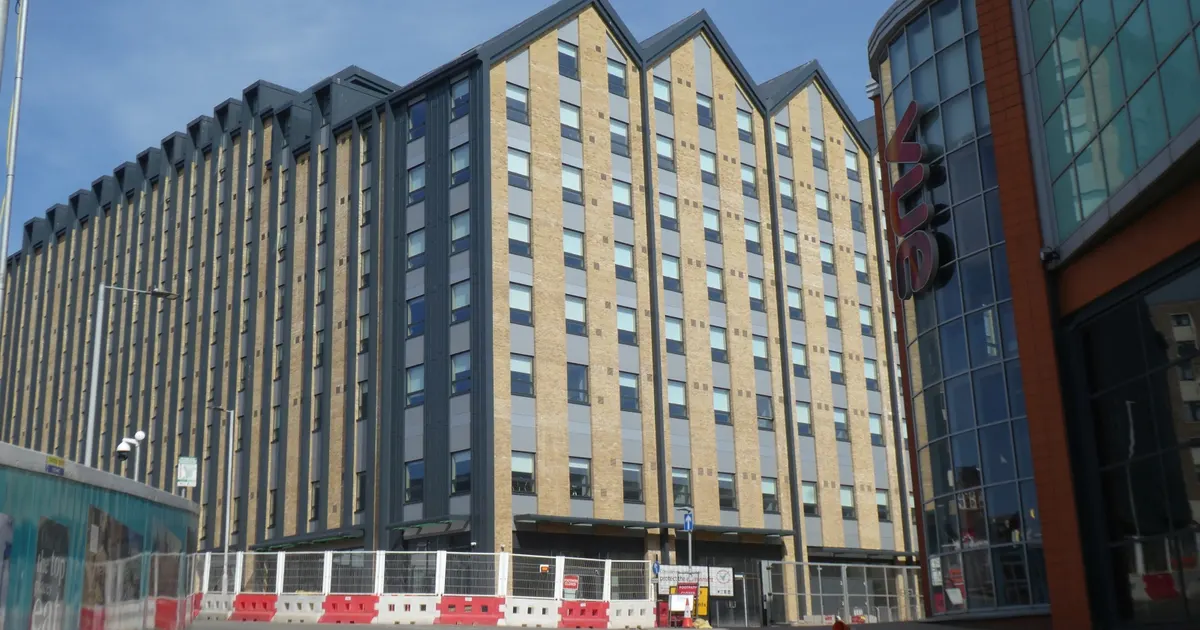
Alternative property investments in the UK are buildings that sit outside the three traditional commercial sectors of offices, shops and industrial units. The usual list covers purpose-built student accommodation, care homes and other healthcare property, self-storage, build-to-rent blocks, hotels, ground rents and car parks. Each one earns its income from a specialist use, which is why it behaves differently from a standard office lease and why an investor needs to ask different questions before putting money in.
Below we explain what counts as an alternative sector, how the main types make their money, the routes private investors use to get exposure and the risks that come with property run as a business. Two rule changes, one on ground rents and one on furnished holiday lets, show how quickly the sums in some of these sectors can shift. First, the definition.
What counts as alternative property?
For decades, “mainstream” UK property meant offices, retail and industrial. Anything else was filed under “other”. Many of those other uses have since grown large enough to be valued, let and traded as sectors in their own right, and fund managers now report them separately.
What links them is that the building only earns money while a specialist use runs inside it. A student block needs students every September. A care home needs residents, trained staff and registration with the regulator. A self-storage centre lets hundreds of small units on rolling contracts instead of one floor on a ten-year lease. That tie between the property and the business inside it is the main difference from conventional commercial property, which our commercial property investment guide covers sector by sector.
The main types of alternative property
Purpose-built student accommodation
Student blocks are let room by room, normally on contracts that run for an academic year. Income depends on the university nearby, how many UK and overseas students it recruits, and how much new supply is going up in the same city. Some blocks are let directly to students. Others are leased to a university, or run under a nomination agreement where the university commits to filling a set number of rooms, which moves part of the letting risk away from the owner.
Care homes and healthcare property
This group takes in care homes, retirement housing, GP surgeries and private hospitals. Care homes are often owned by a landlord and leased to an operator for 20 years or more, with rent reviews linked to inflation. The rent is only as good as the operator paying it. Occupancy, wage bills, the fees local authorities pay for funded residents and the home’s inspection rating all decide whether the operator can keep up with the lease, and in England care homes must be registered with the Care Quality Commission.
Self-storage
A self-storage centre has more in common with a hotel than a warehouse. Customers rent units by the week or month, so the operator can change prices and fill space quickly, and occupancy can fall just as fast. Demand comes from people moving house, small businesses holding stock and students between terms. The larger operators usually own and run their sites rather than leasing them to a tenant, so an investor is buying into the trading performance as much as the bricks.
Build-to-rent and other residential
Build-to-rent means apartment blocks designed and kept by a single owner for long-term letting instead of being sold flat by flat. They come with on-site management and shared space such as gyms or co-working rooms. Supported housing and social housing leased to housing associations sit close by in this category, as do large portfolios of shared houses.
Ground rents
A ground rent investment buys the freehold of a leasehold building and collects the yearly ground rent from each flat. For years it was sold as a quiet, long-dated income stream. The Leasehold Reform (Ground Rent) Act 2022 changed that for new stock. For most new long residential leases granted in England and Wales on or after 30 June 2022, ground rent cannot exceed one peppercorn a year, which in practice means nothing; retirement homes followed on 1 April 2023, according to the government guidance on the Act. Leases granted before then are generally untouched by that Act. Leasehold law has kept changing since, though, so anyone weighing up an existing ground rent portfolio needs current legal advice on the specific leases.
Hotels, holiday lets and leisure
Hotels are either leased to an operator for a fixed rent or owned under a management agreement, where the investor takes the trading profit or loss and a hotel company runs the building for a fee. Holiday lets are the small-scale version. Their tax position changed in 2025, when HMRC’s furnished holiday lettings rules stopped applying from 6 April 2025 for Income Tax and Capital Gains Tax, and from 1 April 2025 for Corporation Tax. Former holiday lets are now taxed under the same rules as any other property business, which removed several reliefs owners had built into their sums.
Car parks, data centres and energy land
Car parks, petrol filling stations, telecom masts, data centres and farmland leased for solar panels or battery storage are also treated as alternatives by many investors. Data centres have grown into a large market of their own, with risks around power supply and changing technology that look nothing like those of a student block.
Why investors look beyond offices and shops
The main draw is income tied to everyday need rather than to the business cycle. Students arrive each autumn, older people need care, and households move and store belongings whether or not companies are hiring. None of that makes these sectors immune to a downturn. It means they react to different pressures from an office block in a city centre, where demand rises and falls with employment and working habits.
Lease length matters too. Healthcare and some hotel and student deals use leases of 20 years or longer, frequently with rents reviewed in line with inflation, usually subject to a cap and a floor. Long, index-linked income is attractive to pension funds and insurers, and their buying is one reason the sectors became mainstream.
Then there is diversification. An investor whose pension already holds offices and shops may want income that does not move in step with them. Higher quoted returns are sometimes part of the appeal, but in operational property a higher yield usually reflects more work and more risk behind the rent. Our guide to commercial property yields explains how to read the figures you are shown and what each one leaves out.
How to invest in alternative property in the UK
Few private investors buy a whole student block or care home. Smaller direct purchases do exist, such as a single holiday let or a parcel of ground rents, but the owner then carries every operating and legal risk alone. Most people use one of four indirect routes.
Listed REITs and property companies. Several real estate investment trusts listed in London specialise in student housing, healthcare, self-storage or supported housing. Their shares can be bought through a stockbroker or held in a stocks and shares ISA, and sold on the market on any trading day. The share price can drift well away from the value of the buildings, in either direction, and it can be volatile.
Unlisted property funds. These pool money across many buildings, sometimes in one sector. Some are open only to professional, high net worth or sophisticated investors, and many limit how often and how quickly you can withdraw.
Bonds, loan notes and crowdfunding. Here you lend to a developer or operator at a set interest rate for a fixed term, often secured on the property. You are a lender rather than an owner, so your return depends on the borrower being able to repay, not on the building rising in value.
Syndicates and joint ventures. A group of investors buys a single asset with a sponsor who manages it. Minimum stakes tend to be high and the money is usually tied up for years.
Our step-by-step guide to how to invest in commercial property compares these routes across the wider property market, including costs and how easy each one is to exit.
Risks that come with alternative property
The biggest is operator risk. In a conventional lease the tenant runs its own business and pays rent from it. In most alternative sectors the business is the building, so a weak operator, a staffing crisis or a poor inspection report can cut income at short notice. Checking who runs the asset, and for how long they have done it, matters as much as checking the building.
Specialist buildings are also hard to sell and hard to convert. A care home or student block has a narrow pool of buyers, and turning one into something else can mean planning consent and heavy spending. Fewer comparable sales make valuations less certain, and pooled funds holding these assets may suspend withdrawals when many investors want out at once.
Policy can move the numbers overnight. The ground rent cap and the end of the holiday let tax regime both changed the economics of sectors that had been sold as stable. Student housing depends on visa rules and university funding; care homes depend on local authority fee rates and minimum wage rises. Building standards, fire safety rules and energy efficiency requirements can also force spending that the original plan did not include.
Concentration is the last one to watch. One building in one town, run by one operator, is a single bet however long its lease is.
Alternative property compared with buy-to-let
Buy-to-let gives you full control of a property and full responsibility for it: finding tenants, repairs, compliance, mortgage costs and tax. Returns depend on one or two homes in one area. Most alternative property, by contrast, is reached through shares, funds or loans, so you give up control in exchange for a share of a larger, professionally run portfolio and someone else doing the management. Neither route is free of risk, and they suit different amounts of time, money and appetite for hands-on work.
Questions to ask before you invest
- Who operates the building, and what is their track record in this sector?
- Is the income a fixed rent from a tenant, or trading income that rises and falls with occupancy?
- How long is the lease, and how are rent reviews worked out?
- How would you get your money back, and how long could that take?
- Which rule changes, such as tax, visas, care funding or leasehold law, could alter the income?
- What fees are charged, and are they taken before the figure you are being quoted?
Frequently asked questions
Is student accommodation a good investment in the UK?
It depends on the city, the university and the price paid. Blocks near universities with strong recruitment and limited new supply have tended to let well, while oversupplied cities and changes to international student numbers can push occupancy down. Buying individual student rooms or pods sold off-plan has a mixed history and is often hard to resell.
Can you hold alternative property in an ISA?
Shares in listed real estate investment trusts can be held in a stocks and shares ISA. Direct property, unlisted funds and most loan notes cannot, although some crowdfunding and lending products qualify for the Innovative Finance ISA. Check the product’s own documents before assuming it does.
Are alternative property investments safe?
No property investment is safe in the sense of protecting your capital. Alternative sectors add operating and liquidity risk on top of the usual property risks, so they suit money you can leave invested for several years and afford to lose part of.
To see how alternative sectors sit within the wider market, visit our commercial property hub, where you can compare property opportunities that match your investment level and eligibility.
This article is general information only and is not financial advice. Property values and income can fall as well as rise, alternative property can be difficult to sell quickly, and you could lose some or all of the money you invest. Past performance is not a guide to future returns. If you are unsure whether an investment suits you, speak to an independent financial adviser.